Briefings, articles and event alerts from our team on the issues shaping Uganda's legal, tax and regulatory environment.
TASLAF Advocates is a Global Practice Guide Contributor to Chambers and Partners’ Private Equity 2026. Our Uganda chapters explore private equity transactions, regulatory developments, fund structuring, governance and tax considerations.

Two-day symposium in Kampala (24–25 September 2026) on “Navigating a New Legal Era – NGO Compliance under Uganda’s Protection of Sovereignty Act, Tax Amendments and Employment Reforms.”
In Spotclean Dry Cleaners Limited v Spot Wash (SMC) Limited [2026] UGCommC 405, the High Court held that a registered company name and trademark did not shield the later entrant from infringement. We unpack what the decision means for brand clearance, URSB registration, goodwill and the real cost of a branding dispute.
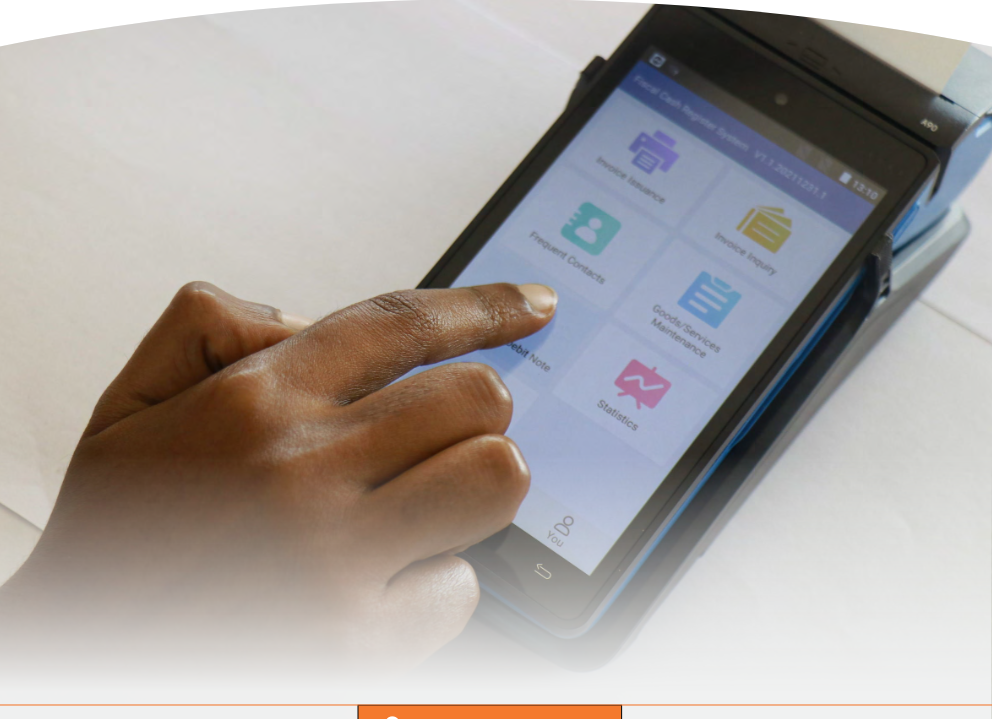
EFRIS is no longer a VAT-only issue. General Notice No. 2218 of 2025 extends mandatory e-invoicing to businesses in 12 designated sectors from 1 July 2025 — including many that are not VAT-registered. We set out who is caught, the UGX 10 million exclusion, and the penal tax exposure for getting it wrong.
Section 19(2)(d) of the Income Tax Act exempts genuine travel allowances and reimbursements from PAYE — but only where the payment relates to official travel and does not exceed the actual or expected cost. We set out when a per diem becomes taxable and the records employers need to defend a URA assessment.
In Kasajja Brian v Attorney General and Inter-Aid Uganda, the High Court held that recognised refugees holding a valid Refugee Identity Card may work in Uganda without a separate work permit, and permanently restrained immigration authorities from arresting or prosecuting them for doing so.
In Ambitious Construction Company Limited v URA, the High Court held that Uganda's 30% EBITDA interest limitation under Section 25(3) of the Income Tax Act applies to net interest expense — not gross — aligning Uganda's rule with OECD BEPS Action 4 and providing welcome clarity for taxpayers with borrow-to-on-lend and intra-group financing arrangements.

URA, in collaboration with the Uganda Manufacturers' Association, has invited manufacturers to submit expressions of interest for inclusion of industrial inputs and raw materials under the duty remission scheme for FY 2026/2027. Applications must reach URA by 19 June 2026 to be considered for the first Gazette in July 2026.
The Tax Appeals Tribunal in Kuku Foods Uganda Limited v URA (TAT Application No. 54 of 2025) confirmed that a 50% or greater direct or indirect change in ownership of a Ugandan company can trigger capital gains tax on the Ugandan entity itself — even where it received no sale proceeds and was not a party to the transaction.
NIRA has announced the commencement of registration of foreign nationals residing in Uganda, effective 10 June 2026. Aliens holding valid immigration facilities must register and obtain an Alien Identification Card. This alert covers the legal basis, registration process, post-registration obligations, and consequences of non-compliance.

The Uganda Revenue Authority (URA) has issued a mandatory directive requiring all taxpayers to update their registration details on the URA portal. Effective 1 July 2025, TINs must be integrated with NIN (individuals), BRN (entities) or a foreign tax identification number. Failure to update may disrupt business operations and tax compliance.

The Tax Amendment Acts for the 2026/2027 financial year have been partially assented to by the President. The VAT, Tax Procedure Codes, Stamp Duty, Lotteries and Gaming and External Trade Acts take effect on 1 July 2026. This briefing unpacks the key changes and their implications for taxpayers, businesses and organisations operating in Uganda.

The Employment (Amendment) Act, 2025 marks one of the most significant reforms to Uganda’s labour framework since 2006 — extending protections to domestic and casual workers, broadening the workplace definition, codifying dignity-at-work, regulating labour externalisation, and fundamentally restructuring dismissal and termination law.

Uganda Revenue Authority’s voluntary disclosure window for foreign income and assets closes on 30 June 2026. Under the Convention on Mutual Administrative Assistance in Tax Matters (Implementation) Act, 2023, URA now receives financial data from over 125 countries. Affected tax residents should act now.

The Tax Appeals Tribunal in Techno Three Uganda Limited v URA (TAT App. No. 009 of 2025) ruled that the 30% EBITDA interest deduction cap under section 25(3) of the Income Tax Act does not apply where the taxpayer’s affiliates are dormant — adopting a substance-over-form, purposive approach.

The Protection of Sovereignty Act, 2026 passed Second and Third Reading on 5 May 2026 and awaits Presidential Assent. It creates a registration, declaration and returns regime for ‘agents of foreigners’ — with material implications for INGOs, development agencies and foreign investors.